

MyCard - Contactless Payment
by Road Dogs
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- $17.99
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
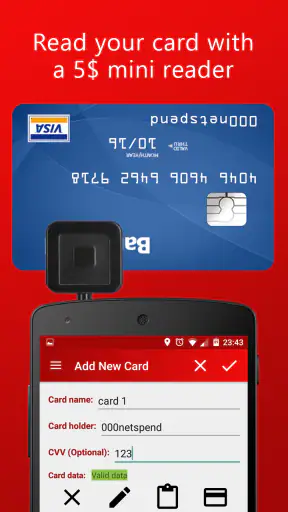
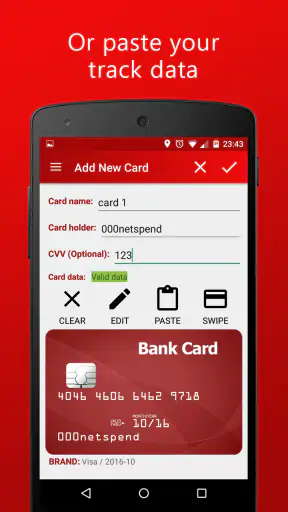
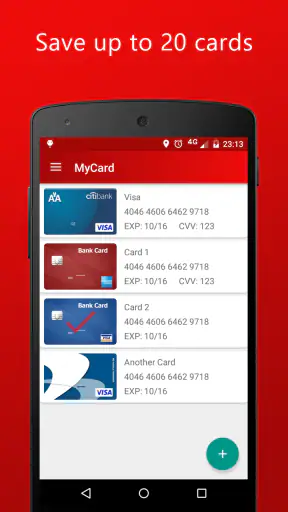
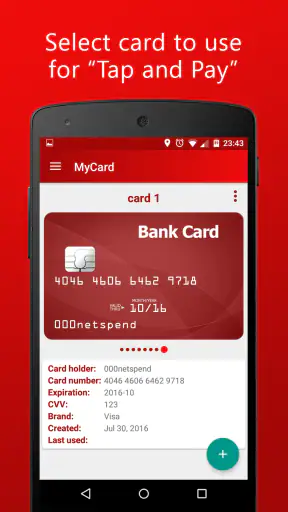
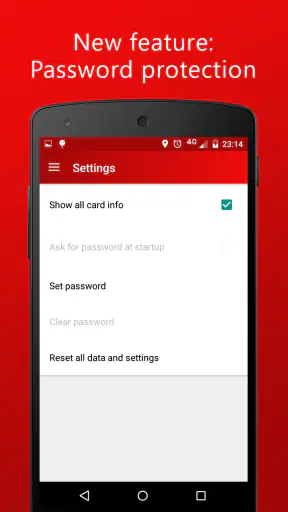
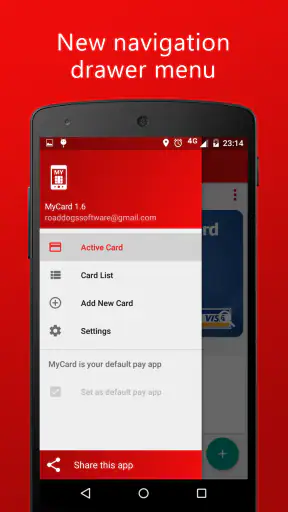
 Analysis by Getfullapps
MyCard - Contactless Payment is an unusual finance app because its entire promise is focused on one practical idea: turning a compatible phone into a contactless bank card. I found that appealing in principle, especially for short trips, quick purchases, or anyone who dislikes carrying a wallet. At the same time, this is not the kind of app I would recommend casually to every smartphone owner. Its value depends heavily on whether the phone, payment setup, and places where you shop work smoothly together.
My overall view is that MyCard is best understood as a focused payment tool rather than a complete banking service. It does not try to replace budgeting, online banking, money transfers, or a physical card in every situation. Instead, it aims to make the phone itself the thing you present at a contactless terminal. That narrow focus is both its most useful quality and its biggest limitation.
A simple idea with a very specific purpose
Road Dogs developed MyCard as a finance app for people who want to use their mobile device at contactless payment points. The short name, MyCard, makes the intention clear: the phone is meant to stand in for a bank card during an in-person transaction. In my experience, that kind of direct purpose is easier to understand than an app overloaded with unrelated financial tools.
The app is available for devices running Android 5.0 or later, which gives it a broad compatibility range on paper. Its current version is 1.21, and it has been available since March 22, 2016. Those details matter because payment apps need to be considered in the context of the phone being used: an older device may meet the operating-system requirement while still offering a less comfortable or less dependable experience than a recent handset.
MyCard is listed at $17.99, so I would not treat it like a casual free utility. That price changes the decision considerably. A person who only wants to experiment with phone payments may find the commitment difficult to justify, while someone who regularly wants a dedicated contactless option may see more value in it. Before paying, I would think about how often I actually use contactless terminals and whether my existing bank or wallet app already handles the same task.
What using it feels like in everyday life
The strongest use case is a routine purchase where speed and convenience matter more than carrying several payment options. Imagine leaving home for a short walk with only a phone and keys. At a café or small shop, the appeal is obvious: instead of searching for a card, I can use the device already in my hand. That is especially convenient when I am already checking a message, following directions, or carrying something else.
There is also a practical benefit for people who prefer a lighter wallet. A phone is easier to remember than a separate card for some users, and a contactless payment app can reduce the number of objects that need to be carried. For a quick local errand, that can make the payment step feel almost invisible.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
However, I would not rely on it as my only payment method without testing it first. Contactless payments involve more than the app alone. The phone must be suitable for the task, the payment terminal must accept the relevant contactless method, and the financial arrangement behind the card must be usable in that environment. If any part of that chain causes friction, the convenience disappears quickly.
My practical advice is to test MyCard with a small, ordinary purchase before depending on it for travel, a large shop, or an urgent situation. Keep a physical card available during the first few outings. That is not a criticism unique to this app; it is sensible whenever a phone is being used as a payment instrument. A low battery, a damaged device, or an unexpected terminal issue can turn a supposedly simple transaction into an awkward one.
Where the app’s focused design helps
MyCard’s strongest quality is its clarity of purpose. I do not open it expecting a full financial dashboard, and that can be refreshing. The app is aimed at the payment moment itself, so the relevant question is simple: can I use my phone like a contactless card when I need to pay?
That focus may suit someone who finds larger mobile-wallet platforms distracting. Many financial apps combine payment cards with rewards, account summaries, transfers, offers, notifications, and other services. Those additions can be useful, but they can also make a basic payment task feel buried. MyCard’s identity is easier to grasp because it centers on contactless use.
Another useful insight is that the app may be more valuable as a backup arrangement than as a total replacement for every card. For example, I could imagine using it for daily low-friction purchases while keeping a physical card for places that do not accept contactless payments. This approach avoids demanding perfection from the app and makes its convenience easier to appreciate.
It can also be a reasonable choice for a person who wants a dedicated payment experience rather than a broad banking application. The distinction matters: MyCard is not something I would choose because I want to track spending or manage a bank account. I would choose it because the act of presenting a phone at a terminal is the feature I care about most.
The important limitations before paying
The first weakness is the price. At $17.99, MyCard needs to provide enough day-to-day convenience to earn its place on the phone. A free payment option already included with a bank account or mobile operating system may be a better financial choice for many people. The question is not whether contactless payment is useful; it is whether this particular app offers enough value beyond alternatives that may cost less.
The second limitation is dependency on compatibility. The minimum Android requirement is 5.0 or newer, but the operating-system version alone does not guarantee that every payment situation will work exactly as expected. Users should consider their handset, the terminals they encounter, and the card or account they intend to use. I would be cautious about assuming that an older compatible phone will deliver the same ease as a newer model.
The third issue is confidence at the checkout. Payment apps need to feel predictable. If I have to wonder whether the phone is positioned correctly, whether the terminal will recognize it, or whether I need to switch to another method, the experience becomes less relaxed than using a familiar physical card. MyCard’s concept is convenient when everything is ready, but a user should still plan for exceptions.
There is also a behavioral trade-off. A phone is a multipurpose device, whereas a card is designed specifically for payment. If the phone is being used heavily, has limited battery, or is difficult to access quickly, the supposed convenience may be smaller than expected. Someone who already carries a wallet and reaches for a card automatically may not notice enough improvement to justify the purchase.
How it compares with familiar alternatives
Compared with a traditional bank card, MyCard offers less physical bulk and potentially faster access when the phone is already in hand. The physical card, however, remains the simpler fallback. It does not depend on the phone being charged, available, or configured for the moment. For people who value reliability above all else, the conventional card still has a strong advantage.
Compared with a bank’s own mobile-payment feature, MyCard faces a more difficult comparison. A banking app may already connect directly to an account the user knows, while MyCard asks the user to adopt a separate payment-focused solution. The independent approach may appeal to someone who wants a dedicated tool, but users should avoid paying twice for essentially the same contactless capability.
Compared with a general mobile wallet, MyCard may feel more specialized and less cluttered. A broader wallet can be better for people who manage several cards, use loyalty passes, or want one place for different digital items. MyCard is more suitable when the central need is straightforward contactless payment and the user does not need a larger ecosystem.
This comparison leads to a clear trade-off: MyCard’s narrow purpose can make it easier to understand, but it also means it has fewer reasons to remain installed if the user already has a reliable payment function elsewhere. I would choose it only after identifying a specific convenience it provides in my own routine.
Who should consider installing it
I think MyCard is most interesting for Android users who frequently make contactless purchases and want their phone to serve as the payment object. It may also suit people who prefer a minimal finance tool instead of a full banking suite. The app’s Everyone age rating makes it broadly approachable, although the practical suitability still depends on the individual’s device and payment habits.
It could be useful for someone who often leaves home with a phone but not a wallet, provided that person is willing to carry a backup during the testing period. It may also appeal to users who want a separate contactless option for everyday errands rather than constantly opening a bank account application.
I would skip it if I rarely use contactless terminals, if $17.99 feels excessive for a single-purpose app, or if my existing bank or wallet already handles phone payments reliably. I would also hesitate if I need one application to manage spending, transfers, multiple cards, or broader financial records. MyCard is not the right answer to those needs because its identity is much narrower.
Before committing, I would check three things in practical order. First, confirm that the phone is running a suitable Android version and is comfortable to use at a terminal. Second, consider whether the places I shop commonly support contactless payment. Third, compare the cost with the payment tools I already have. This short checklist can prevent the common mistake of buying a specialized app for a function already covered elsewhere.
What the community signal suggests
MyCard has reached over ten thousand installs, with a 4.0 average from around two hundred eighty ratings and roughly one hundred twenty written reviews. I see that as a moderate sign of interest rather than proof that it will work equally well for everyone. Payment experiences are particularly dependent on hardware, accounts, and local terminals, so an individual user’s setup matters more than a broad score alone.
The rating does suggest that the app has found a real audience, but it does not remove the need for personal testing. A payment tool can be perfectly useful for one person and inconvenient for another because their phones, banks, or shopping environments differ. I would read the available feedback with that context in mind, looking especially for comments that resemble my own setup and daily routine.
The developer, Road Dogs, has kept the product centered on its contactless-payment purpose rather than presenting it as a general financial platform. That makes the app easier to judge: its success depends on how well it handles the one job it is meant to perform. For me, that is preferable to vague promises, but it also makes the price and reliability questions more important.
My final recommendation
MyCard - Contactless Payment is a focused solution with a clear everyday benefit: it aims to let the phone take the place of a contactless bank card. I like the simplicity of that idea, and I can see its value during quick errands, short outings, and situations where carrying a wallet is inconvenient.
Still, I would not call it an automatic recommendation. The $17.99 price is significant for a single-purpose finance app, and the experience depends on more than installing it. Users need a suitable Android device, compatible payment circumstances, and enough confidence to use the phone at real terminals. A physical card or an existing bank wallet may be the better option for many people.
My verdict is positive but selective: choose MyCard if phone-based contactless payment is a frequent, specific need and you value a dedicated tool. Skip it if you want a complete financial manager, already have a dependable free alternative, or rarely pay by tapping. For the right user, its focused design can make everyday purchases lighter and quicker; for everyone else, the cost may outweigh the convenience.
Pros
- Fast contactless payments at supported terminals
- Convenient access to digital cards in one app
- Reduces the need to carry physical cards
- Transaction history helps monitor recent purchases
- Useful for users who prefer cashless payments
Cons
- Requires a compatible NFC-enabled smartphone
- Availability may depend on country and supported issuers
- Some merchants may not accept contactless payments
- Phone battery loss can prevent access to payment features
- Security depends on proper device and account protection
FAQs for MyCard - Contactless Payment
What is MyCard - Contactless Payment and how does it work?
MyCard - Contactless Payment is designed to let users make payments with a compatible smartphone or wearable device instead of using a physical card. After setting up an eligible card in the app, you can usually unlock your device and hold it near a contactless terminal. The exact payment process, supported cards, and available features may vary depending on your bank, country, device, and the app version.
Is MyCard - Contactless Payment safe to use for everyday purchases?
The app is intended to provide a convenient and secure alternative to carrying a physical payment card. Contactless transactions generally use device security features such as screen locks, authentication, tokenized payment details, or other protections supported by the payment network. However, users should still protect their phone, avoid sharing passcodes, install updates, and contact their bank immediately if the device or payment card is lost.
Which phones, cards, banks, and payment terminals are supported?
Compatibility is one of the most important points to check before downloading MyCard - Contactless Payment. Your phone may need NFC support, a recent operating system, and appropriate security settings. Not every bank or card issuer necessarily participates, and some merchants may not accept every contactless network. Review the app listing and your bank’s information to confirm support in your country before relying on it.
Are there any fees for using MyCard - Contactless Payment?
Downloading or using a contactless payment app may be free, but that does not automatically mean every related transaction is without cost. Your bank, card issuer, mobile carrier, or payment network could apply foreign transaction fees, currency conversion charges, account fees, or other conditions. The app itself may also have region-specific terms, so check the official pricing information and your card agreement before making purchases.
What should I do if a contactless payment fails or my phone is lost?
If a payment does not work, first make sure NFC is enabled, the device is unlocked when required, the selected card is valid, and the terminal accepts contactless payments. Trying again or using another payment method may help, but avoid repeated attempts if your bank shows a pending charge. If your phone is lost, use your device-finding service to lock or erase it and contact your bank to suspend digital payment access.











